- Published On: October 16th, 2026Categories: Medicare, Medicare Advantage

This year’s Medicare open enrollment season – which began October 15th and runs through December 7th – should come with the warning: “Buyer Beware.” The Trump administration and its allies in Congress have made health coverage less affordable and accessible by prioritizing insurance company profits — especially when it comes to the privately-run Medicare Advantage (MA) program.
More than half of Medicare patients are enrolled in Advantage plans, unaware of the major Disadvantages they may discover when it’s already too late. These include limited networks of providers (their own doctors may not participate in these plans), sudden withdrawal from certain markets, and frequent denials of coverage for procedures and care their doctors order. By the time MA patients realize the downside of these plans, it may be difficult for them to switch to traditional Medicare.
Traditional Medicare isn’t perfect. It doesn’t yet cover basic dental, vision, and hearing care – something President Biden tried to add in his Build Back Better Act that was scuttled on Capitol Hill. We still advocate for those coverages as they are important to senior’s overall health. But traditional Medicare offers a much wider network of doctors, hospitals, and other providers – regardless of where patients live. In traditional Medicare, coverage decisions are made without the profit motive that is built into Medicare Advantage — and, unlike MA, the program is administered with minimal overhead. Data from the Congressional Budget Office indicates that “private insurance is increasingly less efficient than Medicare.”
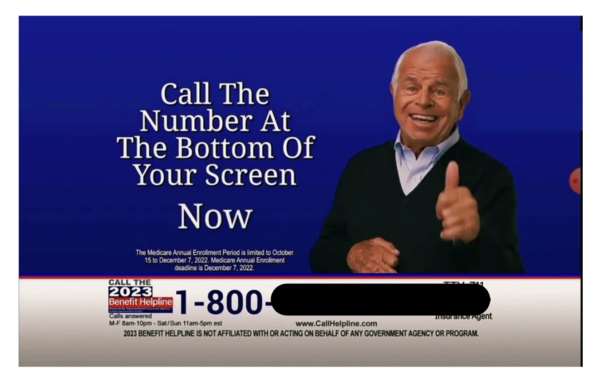
One reason MA has captured a growing share of the market is its misleading advertising, with celebrity pitchmen promising lower premiums and extra goodies – while most enrollees are unaware they are joining a glorified HMO with limited choices. The Biden administration began cracking down on MA’s deceptive ad practices, but next year the Trump administration will be rolling back several marketing safeguards.
“Medicare Advantage plans are being given more room to market aggressively at the very moment that patients face higher premiums, more paperwork, and tighter eligibility rules,” said Anne Montgomery, NCPSSM’s senior health policy expert. “That imbalance could leave people with less coverage, higher costs, and fewer places to turn for care.”
Dynasty’s William Devane in a 2023 Medicare Advantage ad
Medicare Advantage was supposed to provide coverage more efficiently than traditional (or “Original”) Medicare — and save the government money. The opposite has happened. MA is costing taxpayers more per patient, partly because insurers have been overbilling the government to the tune of billions of dollars a year.
The Trump administration has talked about clamping down on MA excesses, but at the same time is rewarding Big Insurance giants like United Health Care, Aetna, and Cigna with more cash. The administration gifted MA insurers a 5.1% payment increase in 2026, far above the 2.2% increase initially proposed under the Biden administration.
In 2027, the administration landed on a 2.48% increase for 2027. In total, these decisions will unlock an additional $38 billion in payments for MA providers who are essentially bilking the federal government and Medicare patients at the same time. The cruel irony is that even this lobbyist-stamped infusion of cash is still not enough to prevent insurers from pulling out of some markets entirely(claiming they can’t make enough money),completely stranding Medicare Advantage patients. Those patients will be forced to find new plans during this year’s enrollment period.
In sum: Trump and the GOP have done everything they can do to make health coverage less accessible and affordable for people of all ages, including seniors. Beginning in 2027, the Medicaid cuts and work requirements enacted in Trump’s “Big, Ugly Bill” will take full effect, threatening coverage for many adults (including ‘near seniors’ aged 55-65) who receive coverage through the Affordable Care Act (ACA). Trump/GOP healthcare policies are projected to strip millions of Americans of health coverage in the coming years.
There are also signs that the Trump regime is trying to make traditional Medicare more like Medicare Advantage. Last year it announced a pilot program to use AI bots for determining prior authorizations in traditional Medicare. In July, Republicans blocked a Democratic-led effort to prohibit this practice, which MA plans have been using for a few years now.
“Rather than having trained medical reviewers assess whether a doctor-prescribed treatment or service is necessary, an artificial intelligence algorithm would apparently decide whether Medicare will pay for it. That is scary for beneficiaries. If Medicare denies payment, patients could be left to cover the cost out of pocket.” – Anne Montgomery on the “You Earned This!” podcast
Health care advocates advise that everyone should at least take stock of and review their Medicare plan — the open enrollment period is not only for people who know they want to switch plans. Even beneficiaries who like their current coverage should review their Annual Notice of Change and other plan materials, because plans can change from year to year, especially in this political environment.
When comparing options, we encourage beneficiaries to check:
*Monthly premiums, deductibles, copays, and out-of-pocket maximums;
*Whether their doctors, hospitals, and other providers are in network;
*Whether their prescriptions are covered, and whether they require prior authorization or other restrictions;
*Whether their preferred pharmacy is in the plan’s preferred network;
*The actual limits and costs of supplemental benefits such as dental, vision, and hearing coverage.
A plan that looks inexpensive on paper can become costly if it does not cover certain medications, excludes your preferred providers, or requires burdensome approvals for necessary care. For more information, beneficiaries can call 1-800-MEDICARE, use the Medicare Plan Finder at Medicare.gov, or contact their State Health Insurance Assistance Program (SHIP) for free advice. Setting some time aside to review the options now can prevent unwelcome surprises in 2027.
*********************************
Listen to our Podcast, HERE
Read some of our past blogs on Medicare Advantage HERE
- Published On: October 9th, 2026Categories: Election 2026, Republicans, Senate, Social Security, Social Security Administration (SSA), Trump
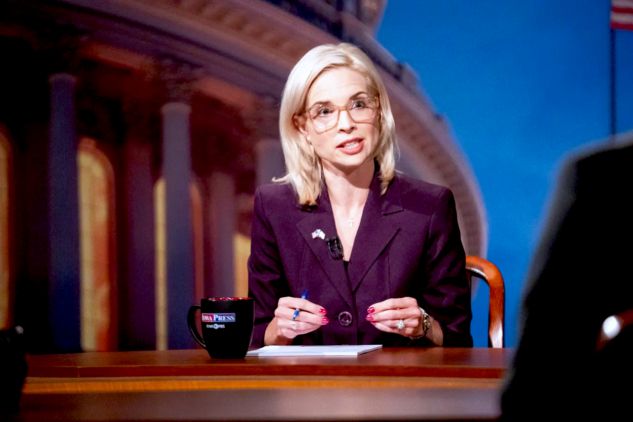
Iowa GOP Senate candidate Ashley Hinson scolds Millennials for not saving enough for retirement
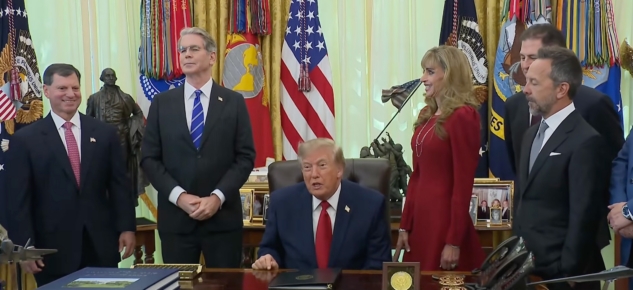
It’s been quite a week for Republicans telling us how they really feel about Social Security – from the President to GOP candidates in key races. On Wednesday, President Trump admitted that he wanted to privatize Social Security “so badly” after he won in 2016, but “Democrats and some Republicans” stopped him, because it was “risky.” You think?
“I wanted to ride with Social Security being fully invested in the stock market, in the first month of my first year. I wanted to do it so badly.” – Trump, 9/7/26
Read here why gambling workers’ earned benefits on Wall Street is such a terrible idea – albeit one that would line the pockets of Trump’s pals in the financial sector.
Trump made the privatization remarks at an Oval Office event touting his so-called “Trump Accounts” for children, which the President has described as “a version” of what Social Security privatization could look like. It wasn’t reassuring that Social Security Commissioner Frank Bisignano – who has overseen the decimation of the agency (SSA) that administers the program – stood beaming by Trump’s side.
Meanwhile, GOP Senate candidates in key races seemed anxious to share their own reckless ideas about Social Security. Houston Public Media reports that Texas Republican senate candidate Ken Paxton called for “cuts to mandatory spending,” which includes Social Security. (Paxton’s comments were captured on audio during a private fundraiser with Washington lobbyists.)
Paxton’s Democratic opponent, James Talerico, opposes benefit cuts and supports raising more revenue for Social Security by requiring wealthy earners to pay their fair share. “Every Texan deserves to know they’ll be able to retire and reap the benefits of Social Security,” Talerico told AARP. “I will fight to ensure all Americans can afford to retire and stand up against any and all attacks on Social Security.”
In Iowa, Republican Senate candidate Ashley Hinson, now a member of the U.S. House, said in 2020 that she was “open” to raising the Social Security retirement age for today’s younger adults – a huge lifetime benefit cut. In an apparent attempt to alienate younger voters even more, Hinson chastised Millennials for failing to save for retirement, calling them “the worst group of savers” during a debate segment this week about Social Security.
The subtext is that we could cut Social Security if only these youngsters would save more money! Apparently, no one has told Hinson that many Millennials are grappling with exorbitant living costs, crushing student debt, and unaffordable home prices that just might affect their ability to sock money away for retirement. Absent employer-provided pensions (increasingly rare), Millennials will depend on Social Security even more than today’s seniors do. But Hinson is open to making them wait longer to retire.
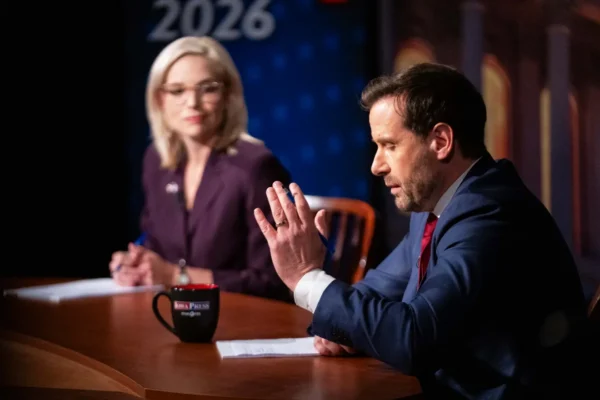
During the Iowa debate, Hinson’s Democratic opponent, Josh Turek, advocated for strengthening Social Security by adjusting the payroll wage cap. “Let’s make sure that billionaires and large corporations are paying their fair share. That will move the needle in a very serious way to keep Social Security solvent.”
Iowa Democratic Senate candidate Josh Turek says: Make the wealthy pay their fair share for Social Security
Hinson and Paxton are not alone among Republican candidates. Michigan Senate contender Mike Rogers “pushed for overhauling Social Security, including supporting measures to privatize the program” as a member of Congress. Yahoo! news reports that “Rogers’ various campaign committees have accepted more than $1.4 million from businesses that would benefit from the privatization of Social Security.”
In New Hampshire, Republican Senate candidate John Sununu helped lead the charge on Capitol Hill during George W. Bush’s campaign to privatize Social Security in 2005, co-authoring a privatization bill with Rep. Paul Ryan. Thankfully, that effort stalled in the face of massive public pushback. But do we want a Social Security privatizer in the next U.S. Senate?
When it comes to Social Security, Democrats are squarely aligned with the public. Polling during the past two years indicates that large, bipartisan majorities of voters support Social Security and do not want to see it cut or privatized. These polls further suggest that people are willing to pay more for Social Security if it means the program will be preserved for the future.
Many Republicans say they “support” Social Security. But they push proposals – germinated in corporate and billionaire-funded think tanks – to cut and privatize it, which would only jeopardize workers’ retirement security. House Speaker Mike Johnson said, rather cryptically, that Republicans have a “plan” to “fix” the program next year, but hasn’t disclosed exactly what that plan is. This is why we say that Social Security is most definitely on the ballot in November.
With the Social Security trust fund reserves projected to become depleted in 2032 (triggering a huge automatic benefit cut) absent congressional action, members of the next House and Senate must determine the future course of Social Security. We know what the financial elites want: to end the program as we know it. Likewise, we know from polling where the majority of the public stands — but it’s up to voters who want Social Security strengthened to make their voices heard in November.
*************************************************************************************
Check our ratings of your elected representatives on our 2026 Legislative Scorecard.
Instead of meaningful action to lower Americans’ health care costs, Trump has announced yet another publicity stunt. He just promised some 20 million Medicare Part B enrollees a one-time, $90 rebate. Of course, this does effectively nothing to lower Americans’ health care costs, which Trump/GOP policies have made increasingly unaffordable.
The Republicans’ Big, Ugly bill slashed nearly $1 trillion from Medicaid – and the GOP-controlled Congress refused to extend Affordable Care Act tax credits. These actions have put immense upward pressure on Americans’ health care premiums.
NCPSSM’s president, Max Richtman, says the rebates will be ineffective in solving the real problem:
“Trump’s $90 payment will not even begin to offset Americans’ increased health costs, which have been exacerbated by Trump and his party’s policies.” – NCPSSM President and CEO Max Richtman.
Many seniors probably won’t even notice the $90 rebate. Standard Medicare Part B premiums are $2,435 per year in 2026 – and current estimates suggest premiums could increase by about $80 in 2027. $90 is hardly a drop in the bucket.
The Trump rebate joins other sketchy plans masquerading as real policy. TrumpRx comes immediately to mind – a website that simply repackages existing discounts on certain drugs, instead of directly addressing Big Pharma price gouging.
Senator Elizabeth Warren noted that prices for one in four drugs on TrumpRx are actually higher than consumers could get elsewhere. “TrumpRx is one more Trump scam right up there with Trump University, Trump Water, and Trump Steaks,” she said. The same can likely be said for Trump’s Medicare rebates.
Funding for the Trump rebates is suspect, too. The money for the rebates reportedly will be siphoned from a $2 billion fund that was set aside to improve Medicare’s hospital and medical insurance programs.
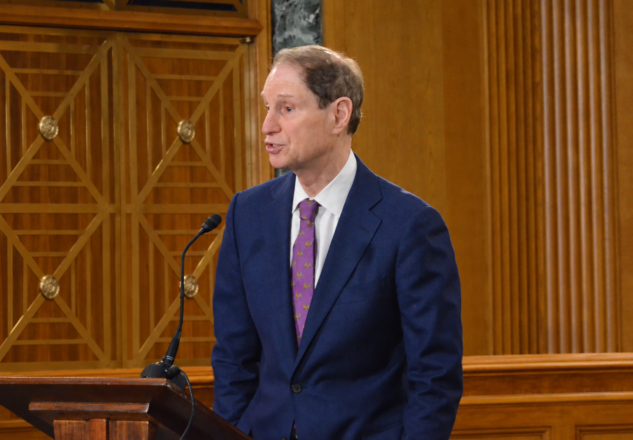
Ranking Senate Finance Committee member Ron Wyden (L) called Trump’s rebate plan “desperate”
As the Washington Post reports, it isn’t even clear that the administration can legally use these funds to issue Trump’s rebates.
“The White House and the Department of Health and Human Services, which oversees the Medicare Improvement Fund, did not respond to questions about the administration’s legal authority to issue the payments.” – Washington Post, 10/5/26
Democrats were quick to dismiss the scheme. Senator Ron Wyden, ranking member on the Senate committee overseeing the Medicare program said, “This is another desperate attempt by a failed president to escape Americans’ revulsion with his failed agenda, amounting to one tank of Trump-inflated gas.”
- Published On: September 1st, 2026Categories: Centers for Medicare and Medicaid Services, healthcare, Medicaid, Medicare, Medicare Advantage
For years, Medicare Advantage (MA) providers have marketed their plans with celebrity endorsements, promises of extra dental, vision, and hearing benefits, and the appeal of low or zero monthly premiums. But for millions of older adults, that illusory promise of stable coverage is colliding with a harsh reality.
Unsatisfied with profits, insurance giants like Humana, United HealthCare and Aetna are pulling out of some markets entirely, leaving Medicare Advantage patients stranded. People enrolled in these plans will be forced to look elsewhere for their coverage in 2027.
We have often criticized Medicare Advantage insurers for putting profits ahead of patients. Humana’s CFO just confirmed it:::
“Increasingly, we’re very much focused on the capital returns of the plan.” -Celeste Mellet, CFO, Humana
This will be the second year in a row that Humana has downsized its MA offerings. Going into 2026, the company scrapped plans in three states and 194 counties, affecting roughly 500,000 seniors. Now, Humana has announced additional “targeted plan exits” expected to affect approximately 600,000 enrollees in 2027, as it seeks to prioritize “higher-performing plans” and improve its profit margins.
The pattern should be familiar to observers of venture capital and startups. Companies use attractive introductory offerings, splashy advertising, and consumer-friendly promises to build market share. Once this is established (and competition has been neutralized), plans can be scaled back, repriced, or eliminated — and consumers (or in this case, patients) are left to deal with the fallout.
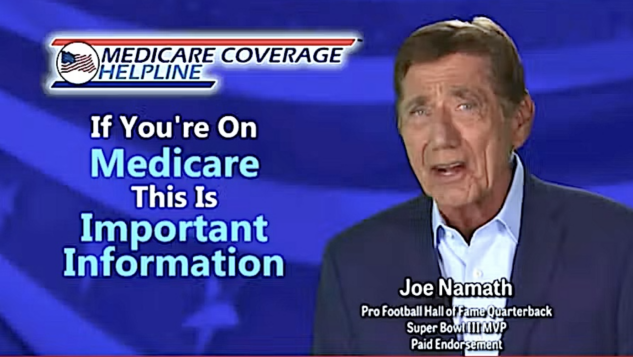
Joe Namath is one of the celebrity spokespeople who hawked Medicare Advantage plans
For Medicare Advantage patients managing cancer, diabetes, heart disease, disability, or multiple chronic conditions, this can disrupt long-standing relationships with doctors and specialists – and create real uncertainty about whether necessary care will remain available and affordable.
Humana is not alone in this trend. A recent Johns Hopkins analysis found that approximately one in 10 people enrolled in Medicare Advantage HMO and PPO plans — about 2.9 million beneficiaries — were forced to disenroll from their current plan for 2026 because the insurer exited the market. That is a dramatic increase from the roughly 1 percent annual forced-disenrollment rate reported between 2018 and 2024.
The disruption can be especially severe in rural communities. In these places, MA enrollment is highly concentrated among a small number of insurers. One dominant company abandoning the market can leave beneficiaries in rural areas with scant alternatives. A plan may still be available, but it may not include the same doctors, hospitals, prescription drugs, supplemental benefits, or out-of-pocket costs.
Trump’s Medicaid Work Requirements Will Deprive Millions of Health Coverage
While the private sector shortchanges Medicare patients, the Trump administration and congressional Republicans are wreaking havoc on Medicaid. Trump’s Big, Ugly Bill imposed new work requirements that are already stripping people of health coverage, even though the law’s main provisions don’t take effect until 2027 (conveniently, after the mid-terms).
Justice in Aging’s Natalie Kean says Medicaid work requirements do not encourage work
Under new federal rules, certain Medicaid patients will generally need to demonstrate 80 hours per month of qualifying activities* to maintain eligibility. Trump and the GOP framed these requirements as a way to encourage work or curb ‘waste.’ In truth, they create mountains of red tape — and will not ‘encourage work.’ Just look at past experiments with work requirements, which had no impact on workforce participation, but did cause vulnerable people to lose health coverage.
NEWS FLASH: More than two thirds of adults on Medicaid already work, and the remainder are not working due to legitimate barriers such as caregiving, illness, disability, or attending school.
“The new requirements are not going to increase work and they’re going to make people less healthy,” said Natalie Kean of Justice in Aging on a recent episode of our podcast.
“People are going to be in this situation where they’re trying to work, but don’t have healthcare. And then their health is going to get worse, which is going to make it harder for them to work. It’s really a paradox.” – Natalie Kean, Justice in Aging
The stakes are especially high in communities where Medicaid is a central source of care. New York State health officials estimate that at least 475,000 residents could lose Medicaid coverage because of the new work requirements. In New York City, communities in the South Bronx, East Harlem, Brownsville, and parts of Queens may be particularly at risk because so many residents depend on Medicaid for primary care, prescriptions, and home health services.
The Big, Ugly Bill cut nearly $1 trillion from Medicaid. It’s expected to result in up to 10 million people losing their coverage. And for what? So that Trump and his party can shower the wealthy with tax breaks they didn’t need. Most developed nations have some form of universal medical coverage, based on the belief that health care is a human right. The United States is not one of them. In fact, under the current regime, one of the wealthiest nations on Earth is stripping its people of health care to further enrich the already wealthy and big insurance companies who prioritize profits over patients.
——————————————————————————————————————-
*Enrollees are now subject to work and “community-engagement” requirements that could make people repeatedly document work, school attendance, job training, volunteer activity, income, health conditions, or other exemptions in order to keep their coverage.
Listen to our podcast, “Trump’s Big, Ugly Bill: One Year Later” with Natalie Kean of Justice in Aging here.
Related Posts
- Published On: August 14th, 2026Categories: President Franklin D. Roosevelt, Social Security
This post is a reprint of an article published on Substack by NCPSSM President & CEO Max Richtman
When President Franklin D. Roosevelt signed Social Security into law 91 years ago — on August 14, 1935 – he said its enactment was “historic for all time.” FDR was right. Nine decades later, Social Security remains one of the most successful – and most popular – federal programs ever.
In poll after poll, overwhelming majorities of Americans across party lines approve of Social Security – and don’t want to see it cut. Despite public sentiment, there’s been a well-funded, long-term movement to undermine this landmark achievement of FDR’s New Deal. Many on the political right have opposed Social Security from the very beginning.
The 1936 Republican presidential nominee, Alf Landon, called Social Security a “fraud on the working man.” Fast forward 90 years to GOP Senator Ron Johnson (WI) calling the program a “Ponzi scheme,” while his colleague, Republican Senator Tommy Tuberville (AL), refers to Social Security as “a scam.” (The political right apparently cannot abide a successful, self-funded social insurance program that provides basic financial security to retirees, people with disabilities, and their families.)
The 70 million Americans who rely on Social Security would be surprised to hear that their earned benefits are a ‘scheme’ or a ‘scam.’ Social Security has never missed a payment since the very first benefit check was issued to retired legal secretary Ida Mae Fuller in 1940. Fuller herself collected benefits every month until she passed away in 1975 at the age of 100! (Fuller even lived long enough to see Social Security benefits automatically adjusted for inflation.)
Today, nearly half of this country’s seniors rely on Social Security to cover all or most of their living costs. Perhaps that’s why one beneficiary told us, “Thank God for Social Security!” Doesn’t that say it all, especially amid the current affordability crisis? After all, seniors on fixed incomes are paying more for gas, groceries, and housing like everyone else.
Social Security was never meant to be set in stone, like the marble monuments here in Washington. It was expanded over the years to include spousal, survivors’, and disability insurance. President Roosevelt himself described Social Security as “a cornerstone in a structure which is being built but is by no means complete.” Today, the structure needs fortification to continue fulfilling its promise to the people.
Without Congressional action, the program’s retirement trust fund reserves are projected to be depleted in 2032. If that’s allowed to happen, beneficiaries will suffer an automatic benefit cut of about 20%. No one wants that outcome. But that doesn’t mean Social Security is “going broke” – as some claim; it only means that the program needs its financing brought back into balance. This can be achieved very straightforwardly by adjusting the payroll wage cap (now set at $184,500) – and including some taxation of high earners’ non-wage income in Social Security-related taxes.
Democrats on Capitol Hill have introduced legislation to bring more revenue into the program and keep Social Security financially strong for decades to come. Instead, some Republicans and right-leaning think tanks have proposed cutting benefits – by raising the retirement age, means testing, or lowering annual cost-of-living adjustments. But they haven’t put forth any legislation to avert the projected shortfall.
In lieu of introducing legislation, some Republicans (and a few centrist Democrats) prefer to create a fiscal commission to decide the future of Social Security. We oppose this idea, because it would provide individual lawmakers with political cover for cutting benefits. (‘Hey, the commission recommended it, so…’)
Besides, we’ve had enough commissions already. As AARP’s Chief Advocacy and Engagement Officer Nancy LeaMond told a Senate committee this month, “The history of fiscal commissions is littered with good intentions and failed results.”
Most Democrats are ready to move forward without a commission to tell them what to do. Senator Sheldon Whitehouse (D-RI) recently implored his Republican colleagues to “put up or shut up.” He urged GOP members to introduce their own Social Security legislation or to vote on bills like his, which adjusts the payroll wage cap and includes some non-wage income in order to extend trust fund solvency “as far as the actuarial eye can see,” with no benefit cuts. Legislation introduced by Senator Bernie Sanders, Senator Elizabeth Warren, Reps. Brendan Boyle, Val Hoyle, and John Larson would do much the same.
This is the public’s preferred solution, according to the National Institute for Retirement Security (NIRS). “There is a preference for raising revenues over cutting benefits,” NIRS reported after completing a thorough public survey in 2024. “Fully 85% of respondents chose options that protect benefits over benefit reductions.”
As Senator Whitehouse says, it isn’t complicated. Congress must act soon to avert a trust fund shortfall and automatic benefit cut. And the smart solution is there and ready to go. Yet Republicans continue to use straw man arguments. They claim the nation can’t afford Social Security as it now exists because of “debt.” In reality, Social Security is self-funded and does not contribute to the debt. In fact, Social Security is legally forbidden from incurring debt.
Some conservatives insist that Social Security should be privatized – with workers’ contributions gambled in the financial markets instead of safely invested in U.S. government bonds. No doubt, Wall Street fund managers would love to get their hands on the $2.6 trillion currently in the trust fund. But it’s a gamble that working people can’t afford. (Imagine an older worker on the cusp of retirement when the markets crashed in 2008.)
There is another misleading narrative emanating from conversative think tanks and spread by the mainstream media that the reason for the trust fund’s projected shortfall is demographics: declining birth rates coupled with a growing senior population equals fewer workers paying into the program. But, as labor economist Kathryn Edwards points out in an essay for the Roosevelt Institute: the real culprit is the massive income inequality of the past five decades that has deprived Social Security of revenue, driven by economic policies that favor the wealthy and big corporations. We can afford Social Security, Edwards argues, if federal policy is re-fashioned to benefit working people instead of financial elites.
The 91st anniversary is a pivotal moment for Social Security. Social Security is most definitely on the ballot in this year’s midterm elections. The next Congress likely will decide the very future of the program. In fact, Senators elected in 2026 still will be in office when the projected trust fund depletion date rolls around in 2032. The best way to honor Social Security’s successful 91-year legacy is to vote for candidates who support strengthening the program by bringing in more revenue – not by cutting benefits, and without the ‘help’ of a fiscal commission. Social Security truly is on the ballot in 2026! If the next Congress listens to the American people and acts accordingly, FDR’s crowning achievement and its 70 million beneficiaries will enjoy many more anniversaries to come.
******************************************************
Subscribe to Max’s Substack Social Security to the Max!
Watch our documentary about the history of Social Security
Listen to our podcast for Social Security’s 91st anniversary: “A Boomer, A Millennial, and a. Zoomer Walk Into A Studio…”